
Weekly recap of the crypto derivatives markets by BlockScholes.
Key Insights:
With markets pricing in a near certainty (93%) probability for the first rate hike from the Federal Reserve since 2023 in its meeting tomorrow, and odds on Polymarket for the passing of the Clarity Act by the end of 2026 falling to 19%, implied volatility in BTC and ETH options markets is mostly flat.
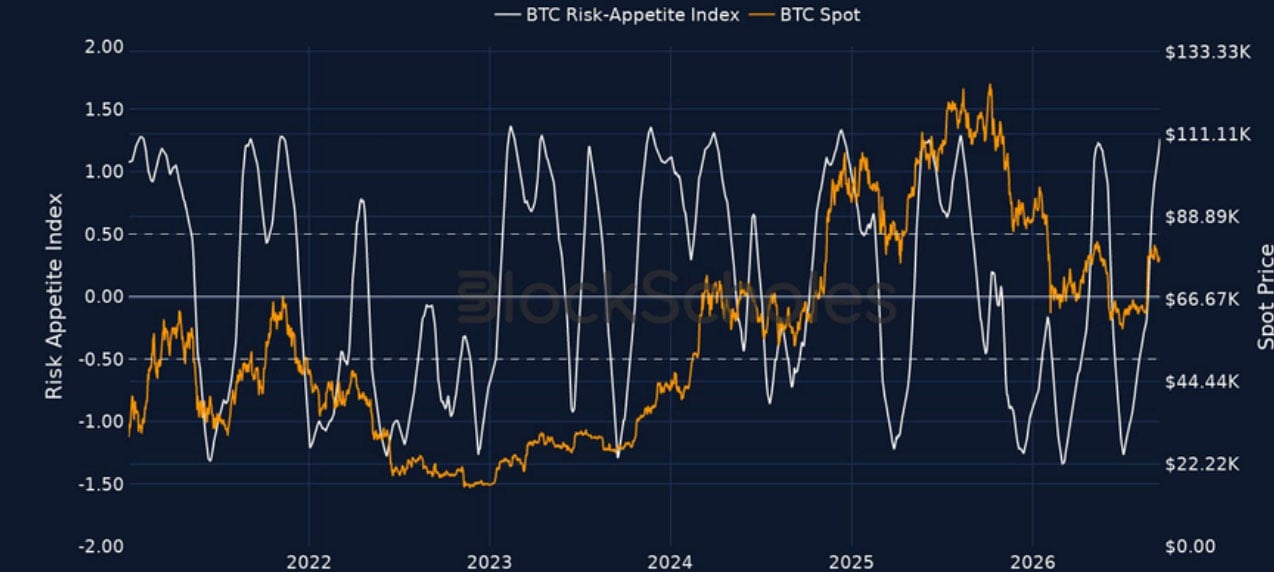
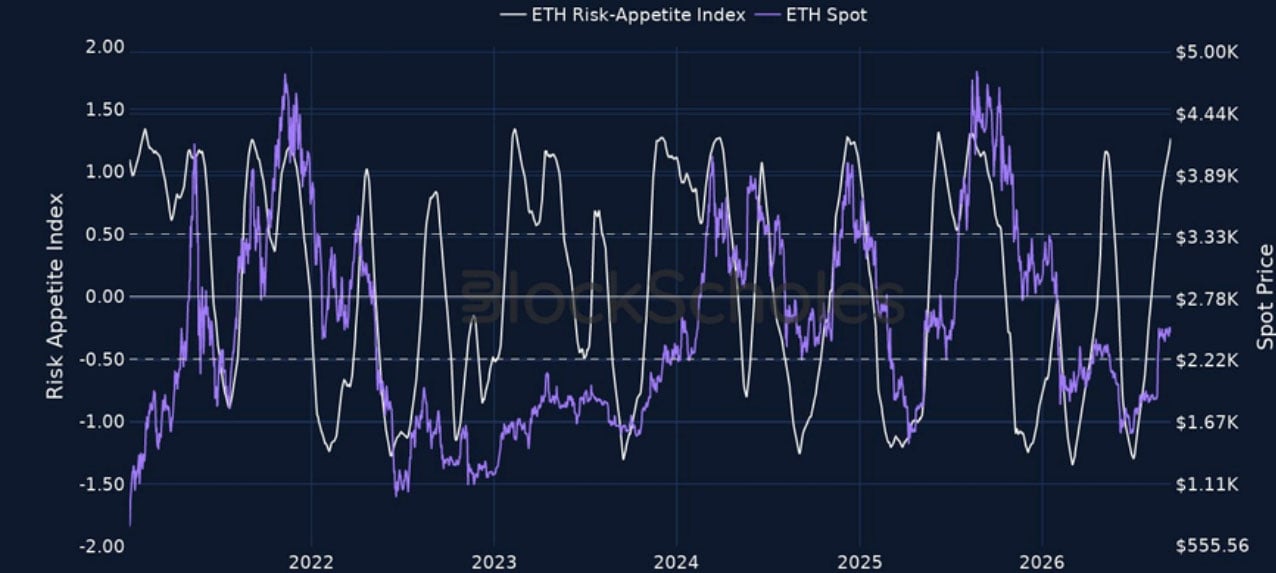
7-day BTC options trade with a very slight volatility premium relative to 14-day options, though overall levels of IV across tenors trade between 38 and 39%. Despite the slightly more negative backdrop, volatility smiles indicate BTC put-call skew trades close to neutral and moderately bullish for ETH. Block Scholes’s Risk Appetite Indexes are, however, approaching levels where risk sentiment has struggled to hold up above in the past.
Block Scholes BTC Risk Appetite Index
Block Scholes ETH Risk Appetite Index
1-Month Tenor ATM Implied Volatility
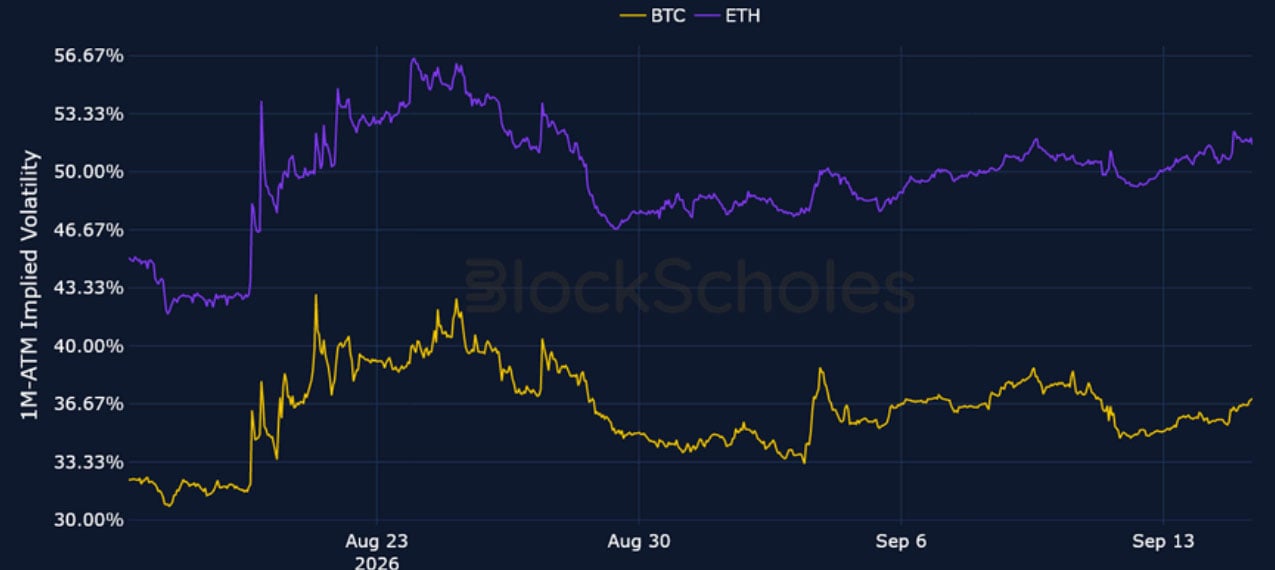
BTC Options
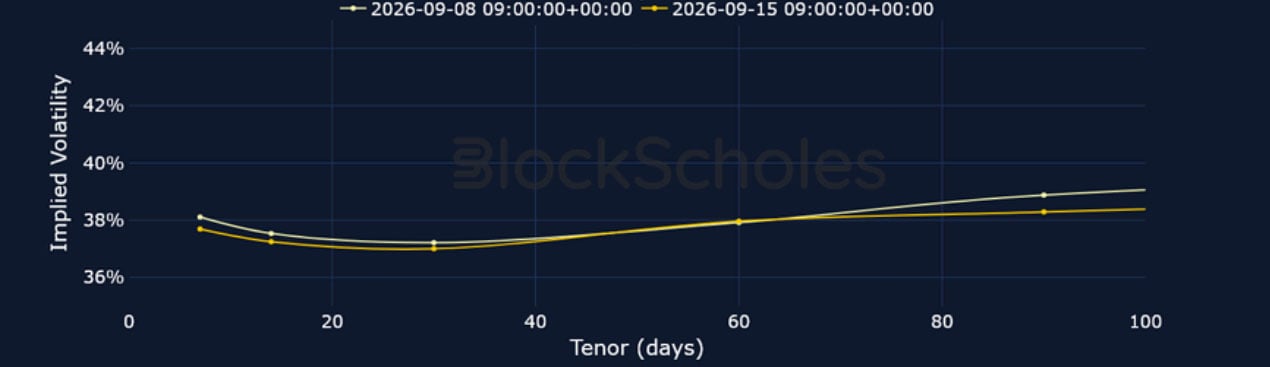
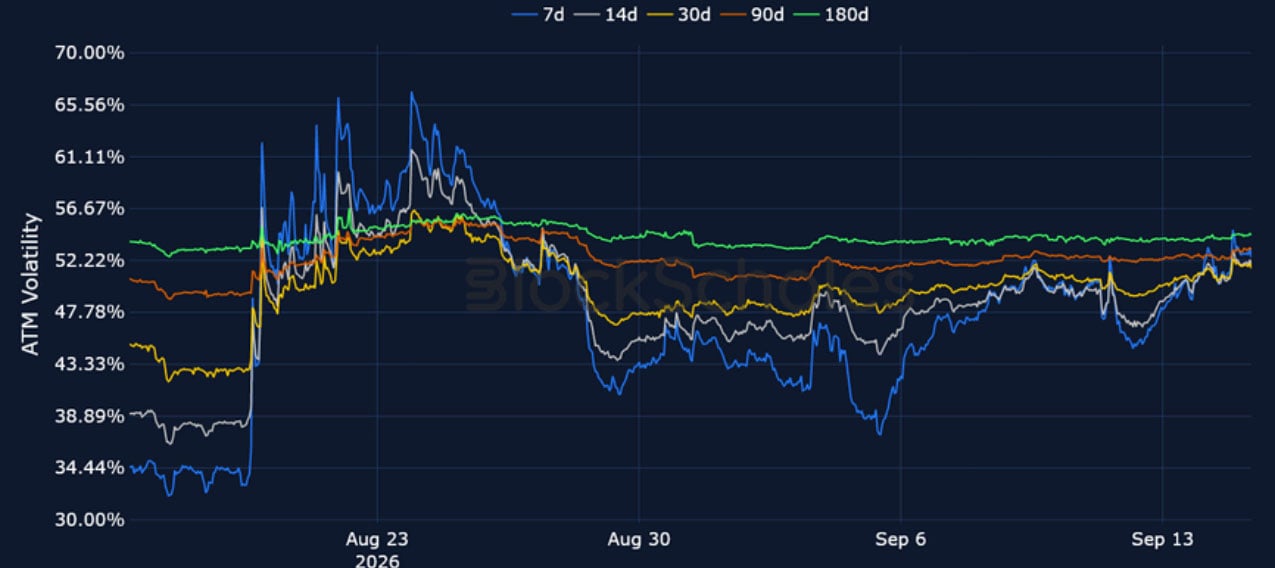
BTC SVI ATM IMPLIED VOLATILITY – BTC’s term structure of volatility is flat ahead of the Senate’s procedural vote on the Clarity Act today and tomorrow’s FOMC meeting, where markets assign a 93% probability the Fed will hike interest rates for the first time since 2023.
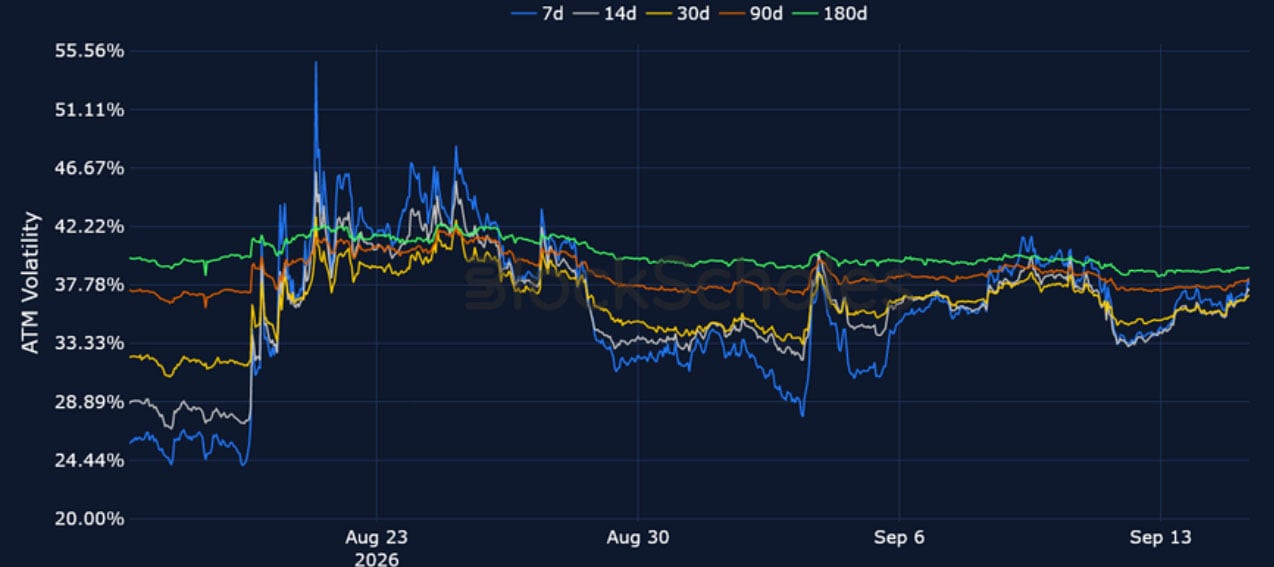
ETH Options
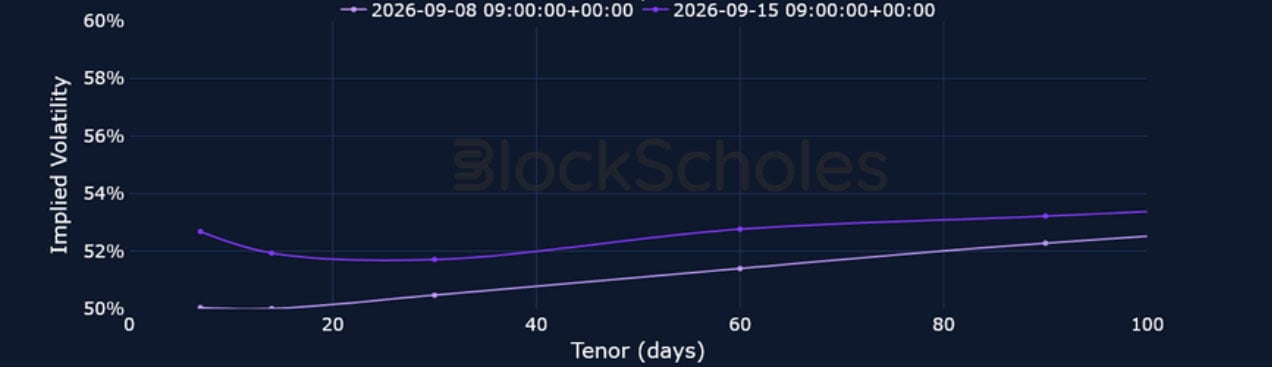
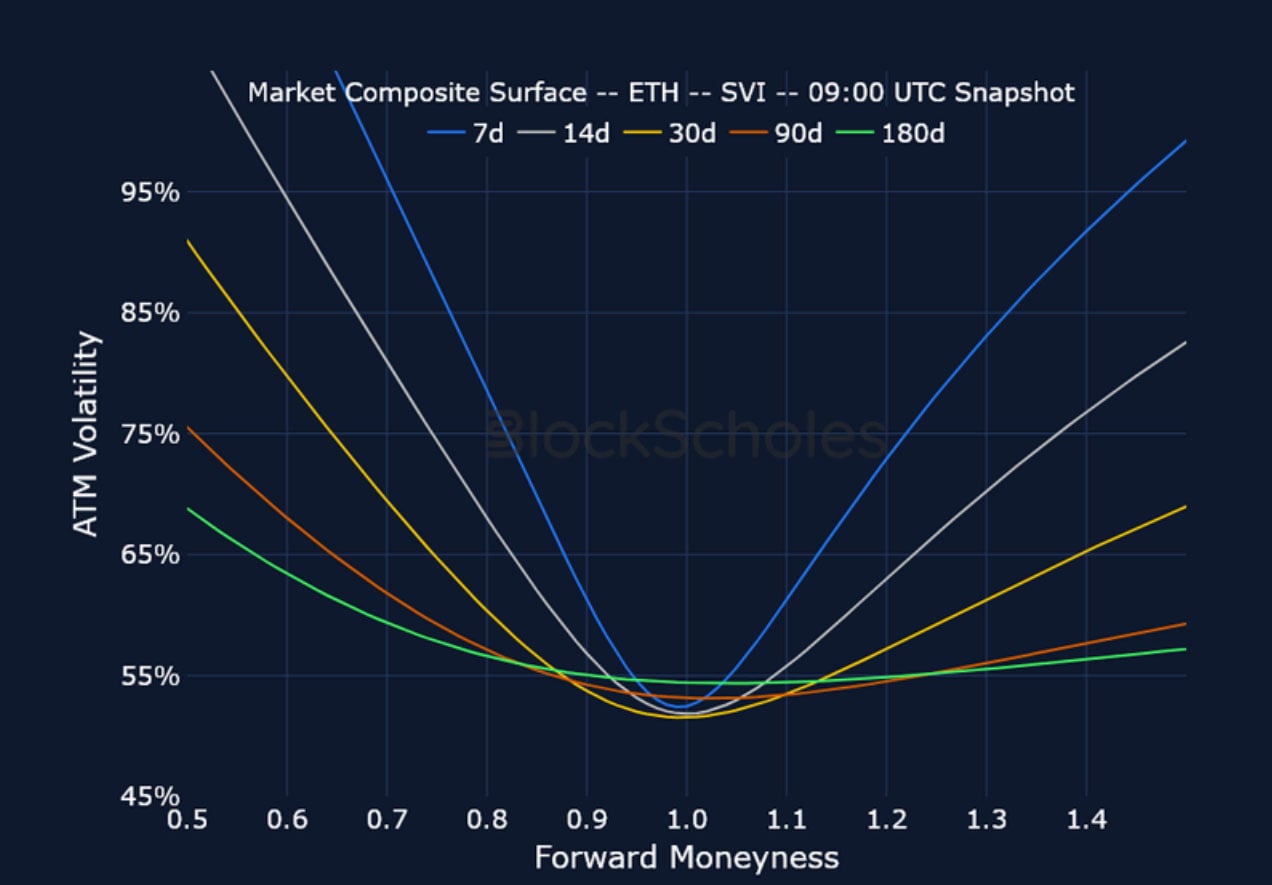
ETH SVI ATM IMPLIED VOLATILITY – Similar to BTC, options traders assign a slightly higher vol premium for 7-day options over 14-day options, though overall levels of IV trade around 52-54% across the term structure.
BTC and ETH Skew
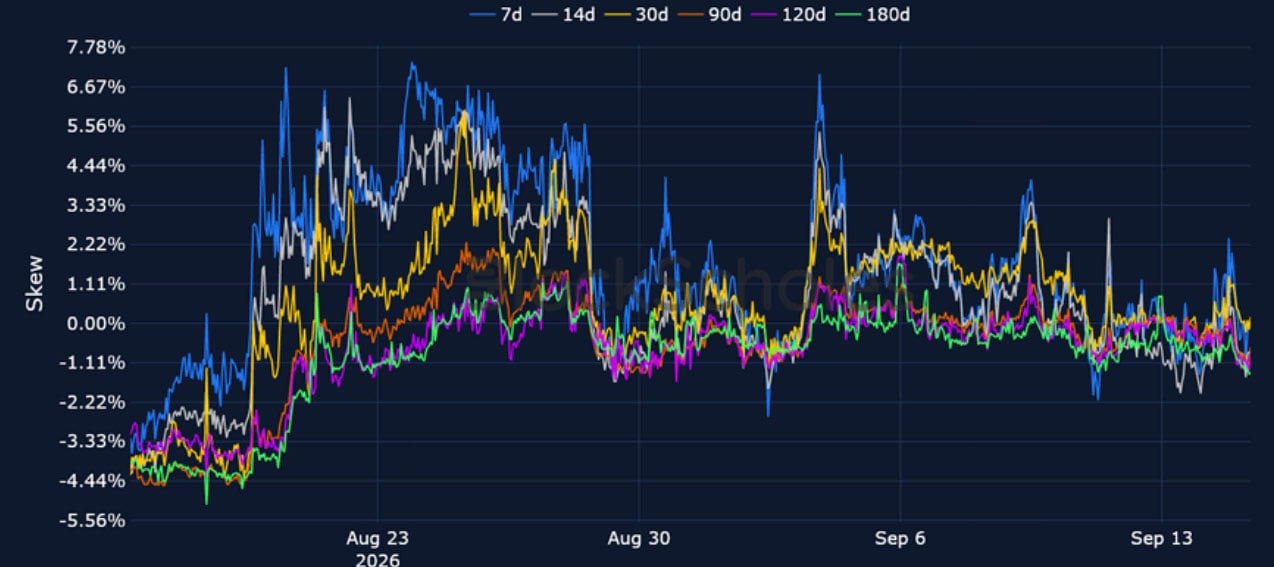
BTC 25-Delta Risk Reversal – With BTC continuing to consolidate below $80K, volatility smiles have traded close to neutral levels, but haven’t yet materially turned bearish over the last two weeks.
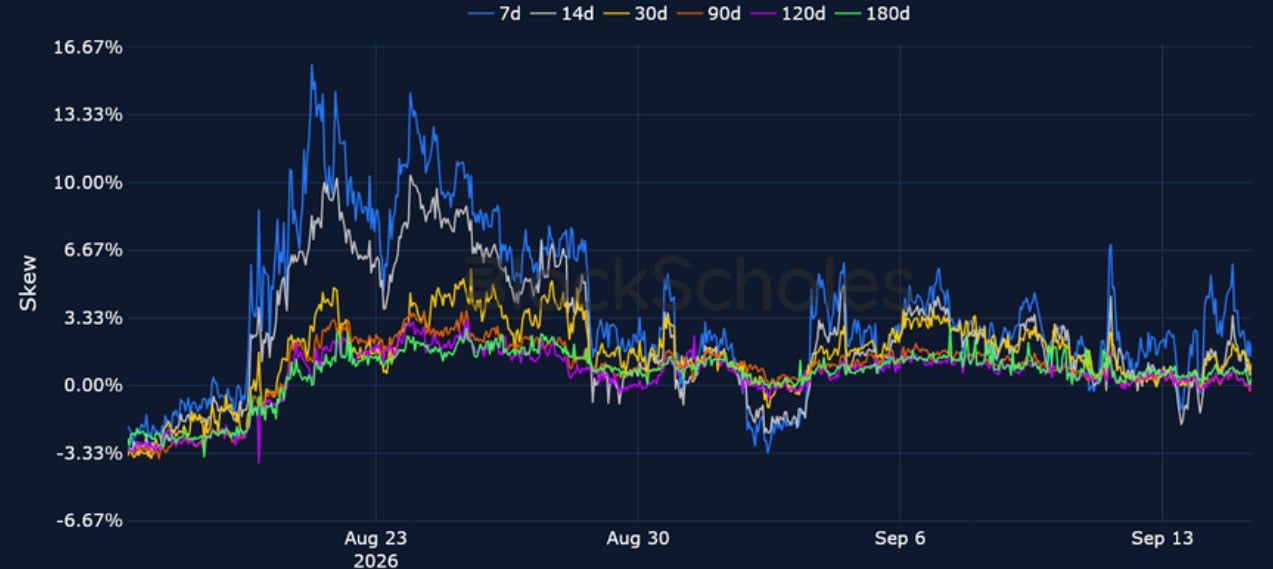
ETH 25-Delta Risk Reversal – ETH has spent the past month trading between $2,300 and $2,600, with options markets continuing to pay a (slight) premium for OTM call options over put contracts.
Market Composite Volatility Surface
BTC SVI – 8:00 UTC Snapshot.
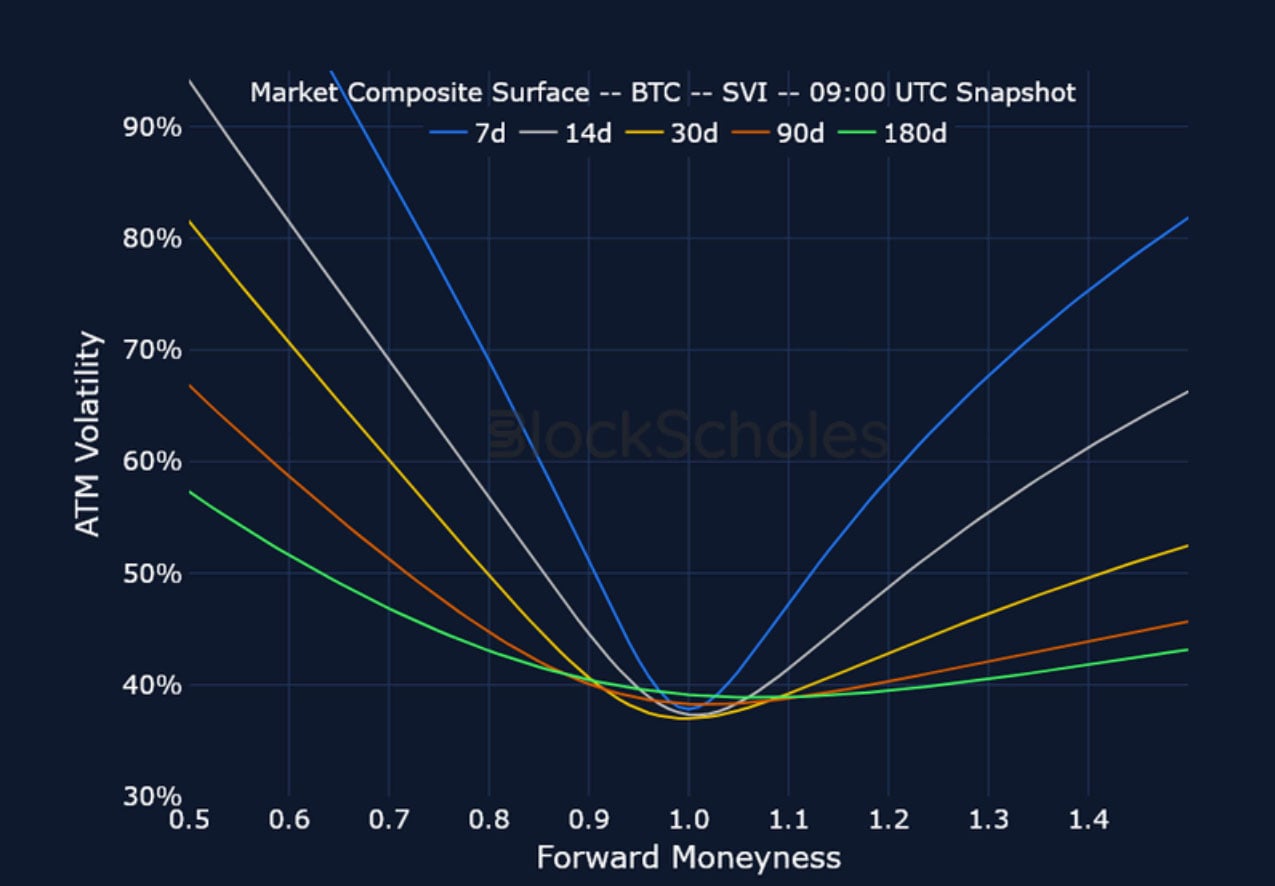
ETH SVI – 8:00 UTC Snapshot.
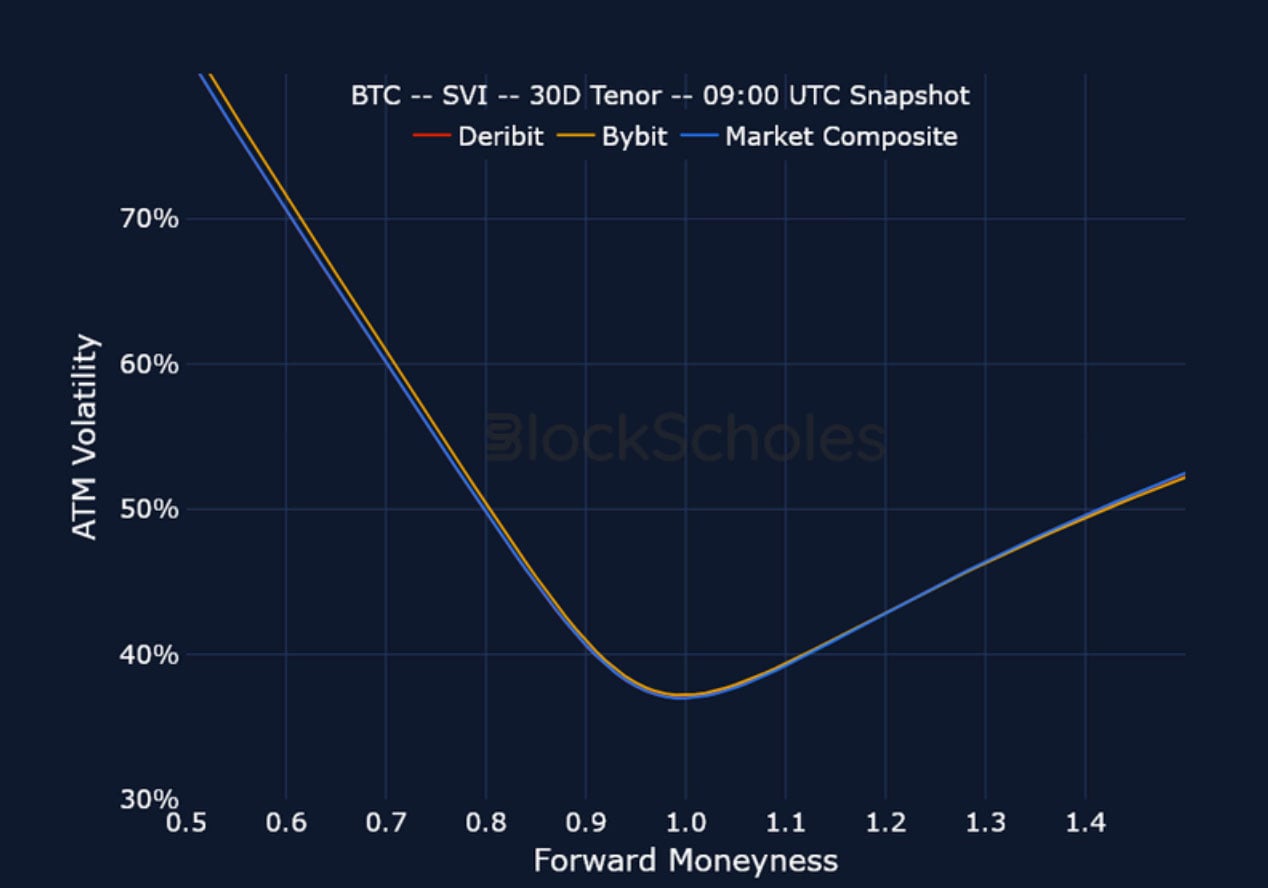
Cross-Exchange Volatility Smiles
BTC SVI, 30D TENOR – 8:00 UTC Snapshot.
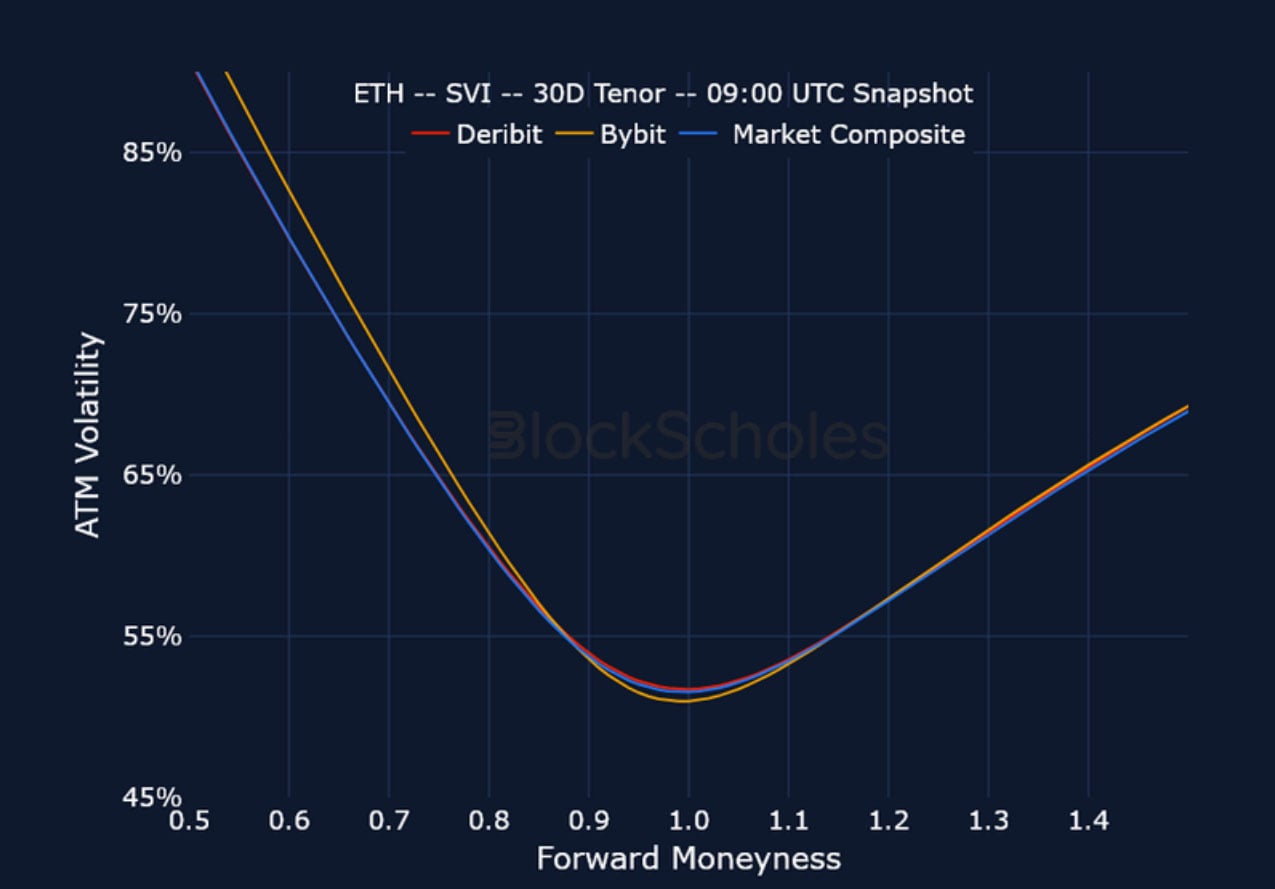
ETH SVI, 30D TENOR – 8:00 UTC Snapshot.
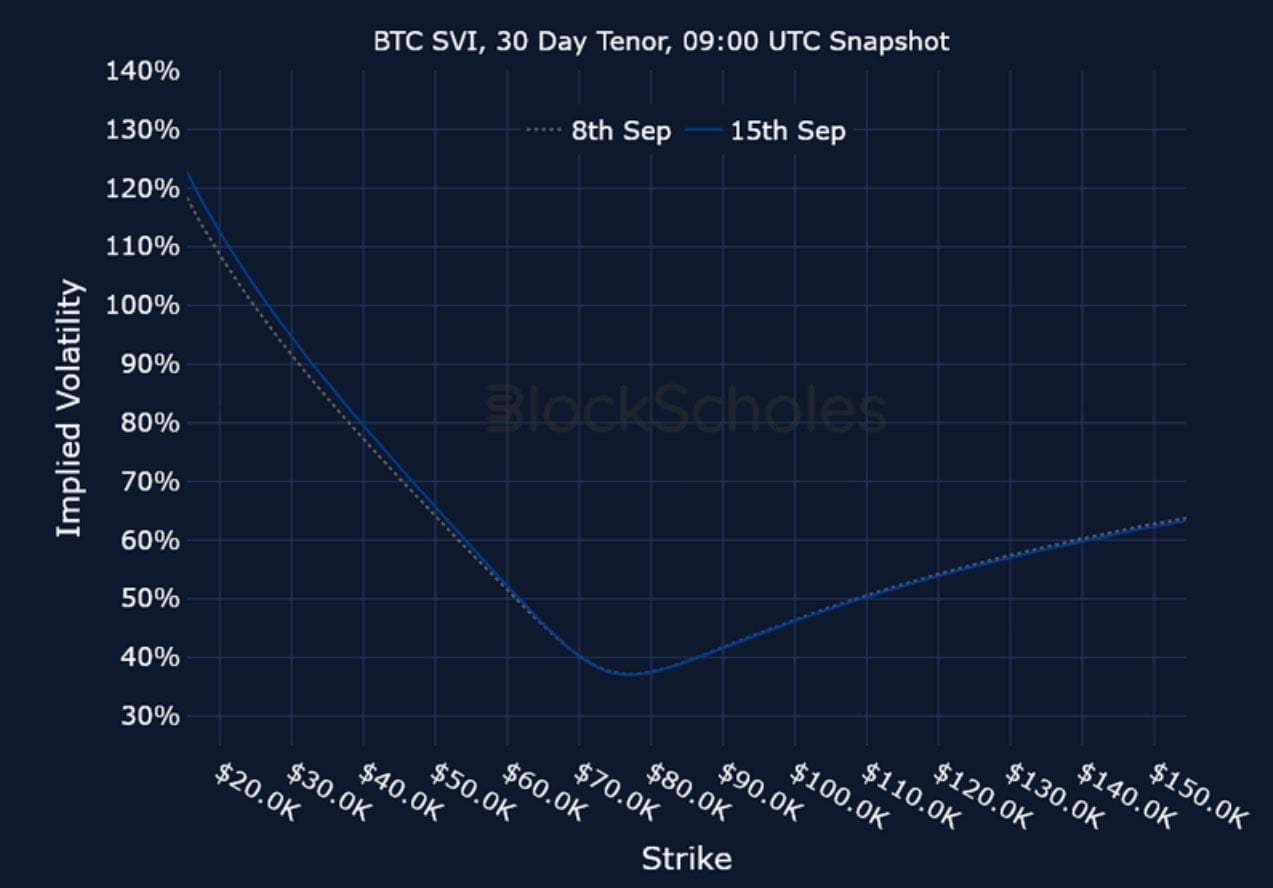
Constant Maturity Volatility Smiles
BTC SVI, 30D TENOR – 8:00 UTC Snapshot.
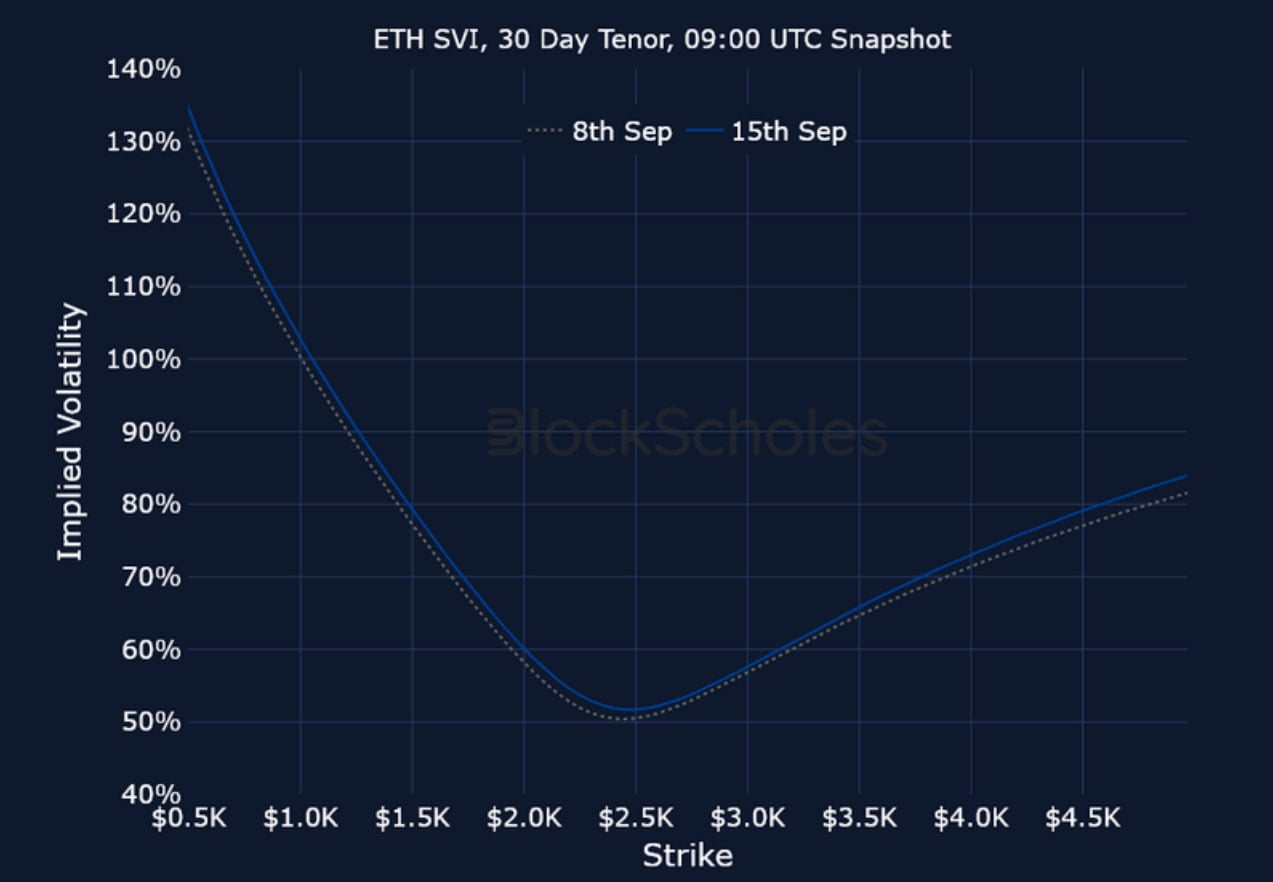
ETH SVI, 30D TENOR – 8:00 UTC Snapshot.
Data Reference
Block Scholes Risk Appetite (BTC/ETH)
Block Scholes’ Risk Appetite index uses a composite spot index price; POST /api/v1/price/index
1-month ATM implied volatility (BTC/ETH)
At-the-money IV at a constant 1-month tenor; forward- looking vol expectations; POST /api/v1/iv/moneyness
Volatility term structure & SVI ATM IV by tenor (BTC/ETH)
SVI-fitted ATM IV across constant tenors (7d / 14d / 30d / 90d / 180d); POST /api/v1/modelparams
25-delta risk reversal / skew (BTC/ETH)
Spread between 25Δ call and 25Δ put IV; a measure of upside vs downside option demand; POST /api/v1/iv/risk-reversal
Market composite volatility surface (BTC/ETH)
BlockScholes composite SVI surface across forward moneyness and tenor, aggregating market-wide options pricing into one clean fitted surface; POST /api/v1/iv/moneyness + POST /api/v1/modelparams
Cross-exchange volatility smiles (BTC/ETH)
Venue-level (Deribit, Bybit) and composite smiles at a fixed tenor, for comparing exchange pricing against the market composite; POST /api/v1/iv/moneyness
Constant-maturity volatility smiles (BTC/ETH)
Like-for-like smile at a fixed tenor across strikes, showing how the smile shifted between dates; POST /api/v1/iv/strike
Disclaimer
This article reflects the personal views of its author, not Deribit or its affiliates. Deribit has neither reviewed nor endorsed its content.
Deribit does not offer investment advice or endorsements. The information herein is informational and shouldn’t be seen as financial advice. Always do your own research and consult professionals before investing.
Financial investments carry risks, including capital loss. Neither Deribit nor the article’s author assumes liability for decisions based on this content.
AUTHOR(S)

Trading with a competitive edge. Providing robust quantitative modelling and pricing engines across crypto derivatives and risk metrics.